
After experiencing bankruptcy, individuals usually face vital challenges in regaining their monetary footing. One of those hurdles consists of accessing personal loans, which are often essential for varied wants like repairs, training, or unexpected bills. This study report aims to provide a comprehensive overview of personal loans for those with bad credit following bankruptcy, analyzing the kinds of loans available, lenders who cater to those circumstances, software methods, and authorized issues.
Understanding Personal Loans
Personal loans are unsecured loans that can be utilized for nearly any objective, ranging from consolidating debts to financing giant purchases. Not like secured loans, personal loans don't require collateral, making them riskier for lenders; this issue typically results in increased interest charges, particularly for borrowers with poor credit score historical past.

The Affect of Bankruptcy on Credit Scores
Bankruptcy has a profound impact on a person's credit rating, usually resulting in a sharp decline. FICO scores can drop by 130 to 240 factors depending on an individual's prior score and the type of bankruptcy filed (Chapter 7 or Chapter 13). This drastic reduction in creditworthiness can make securing loans immensely tough. Generally, a rating beneath 580 is labeled as unhealthy credit score, which is the typical vary for someone rising from bankruptcy.
Types of Personal Loans for Bad Credit
A number of varieties of personal loans could also be available to people with unhealthy credit score following bankruptcy:
- Secured Loans: These loans require borrowers to place up collateral, resembling a car or financial savings account. For those who have almost any questions regarding exactly where as well as the way to use Trulyrichmom, it is possible to e-mail us with our web-page. Because they are backed by tangible property, secured loans typically include lower interest rates compared to unsecured loans.
- Co-signer Loans: Involving a co-signer with good credit can significantly improve the possibilities of loan approval. The co-signer agrees to take accountability for the debt if the primary borrower defaults, which reduces the lender's threat.
- Peer-to-Peer (P2P) Lending: Platforms equivalent to LendingClub and Prosper join borrowers straight with particular person buyers willing to fund loans. P2P loans could also be more flexible relating to credit score requirements, offering another route to traditional lending institutions.
- Credit score Unions and Group Banks: Not like larger financial establishments, credit unions and smaller community banks usually deal with constructing relationships with members and could also be extra keen to increase loans to individuals with lower than stellar credit score histories.
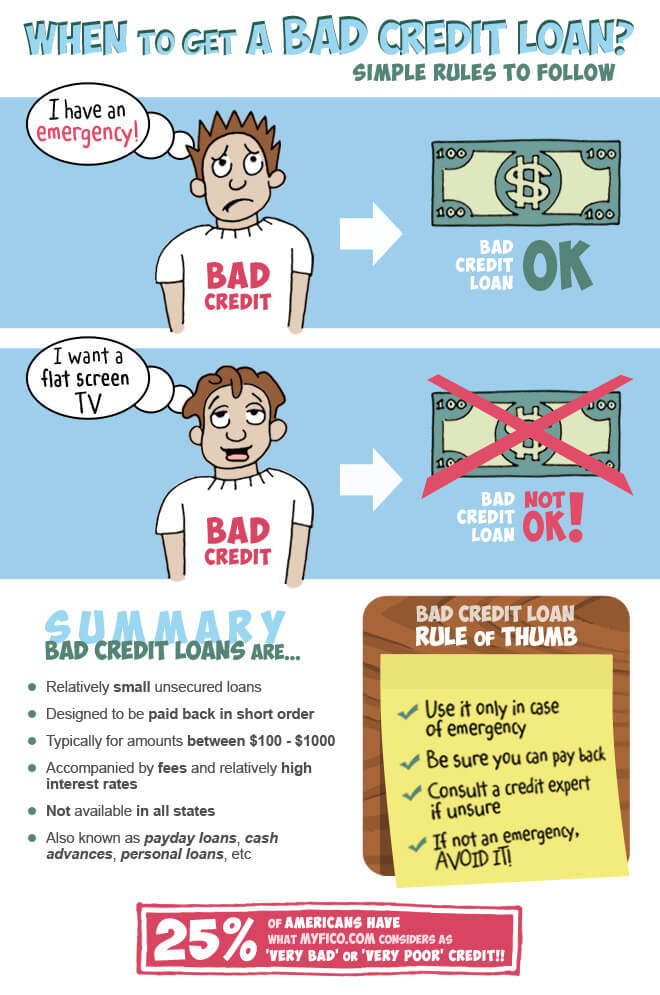
- Payday Loans: While often thought-about a last resort as a result of their exorbitant interest charges and fees, payday loans are readily accessible for fast cash. However, they can lead to a cycle of debt that is hard to flee.
Finding Lenders Prepared to Work with Bad Credit
A number of lenders focus on providing personal loans to borrowers with unhealthy credit. It is essential to research and understand their phrases completely. Some prominent lenders on this category embody:
- Avant: Recognized for accommodating borrowers with lower credit scores. They provide flexible payment phrases and fast funding.
- BadCreditLoans.com: This platform connects borrowers with lenders who're keen to work with those who've dangerous credit score.
- OneMain Financial: They give attention to personal loans with no strict credit rating requirement, and they could supply secured loans to decrease dangers.
- OppLoans: This lender supplies personal loans particularly designed for people with dangerous credit score and has a fast utility process.
Application Strategies for Personal Loans
Securing a personal loan after bankruptcy requires strategic planning:
- Test Your Credit score Report: Earlier than applying, overview your credit report for inaccuracies. Disputing errors may help enhance your rating slightly and improve your possibilities of loan approval.
- Assess Your Financial Wants: Decide the amount wanted and avoid borrowing greater than vital. Understanding how a lot you want will help in discussions with potential lenders.
- Create a sensible Price range: Perceive your income and expenses to ensure you possibly can afford the loan funds. Lenders will assess your Debt-to-Earnings ratio (DTI), which measures how much of your month-to-month revenue goes towards debt payments.
- Analysis Multiple Lenders: Don’t settle for the primary offer. Examine phrases, curiosity charges, and repayment plans among different lenders to search out the perfect possibility.
- Collect Necessary Documentation: Be ready to offer proof of revenue, employment history, and any property which will enhance your utility.
- Consider Prequalification: Some lenders provide a prequalification process the place you possibly can gauge your eligibility for a loan without impacting your credit score score.
Authorized Issues
People seeking personal loans after bankruptcy should be aware of their rights. Beneath the Fair Credit score Reporting Act (FCRA), consumers have the correct to dispute inaccuracies on their credit score studies. Furthermore, lenders are prohibited from denying credit solely based on a person's status of bankruptcy; nevertheless, they will consider the overall credit score history.
It is also essential to be cautious of predatory lending practices, which may be more prevalent amongst individuals with poor credit. At all times read the high quality print and understand terms, fees, and curiosity charges before agreeing to any loan.
Conclusion
Personal loans for individuals with unhealthy credit score put up-bankruptcy are challenging however not unattainable. By understanding obtainable loan varieties, discerning lender choices, employing efficient software methods, and figuring out one's authorized rights, people can find a path again to financial stability. As they work to rebuild their credit, it's crucial to approach borrowing cautiously and maintain prudent financial habits to avoid falling again into disaster. With diligence and knowledgeable alternative, regaining financial well being after bankruptcy is feasible.


